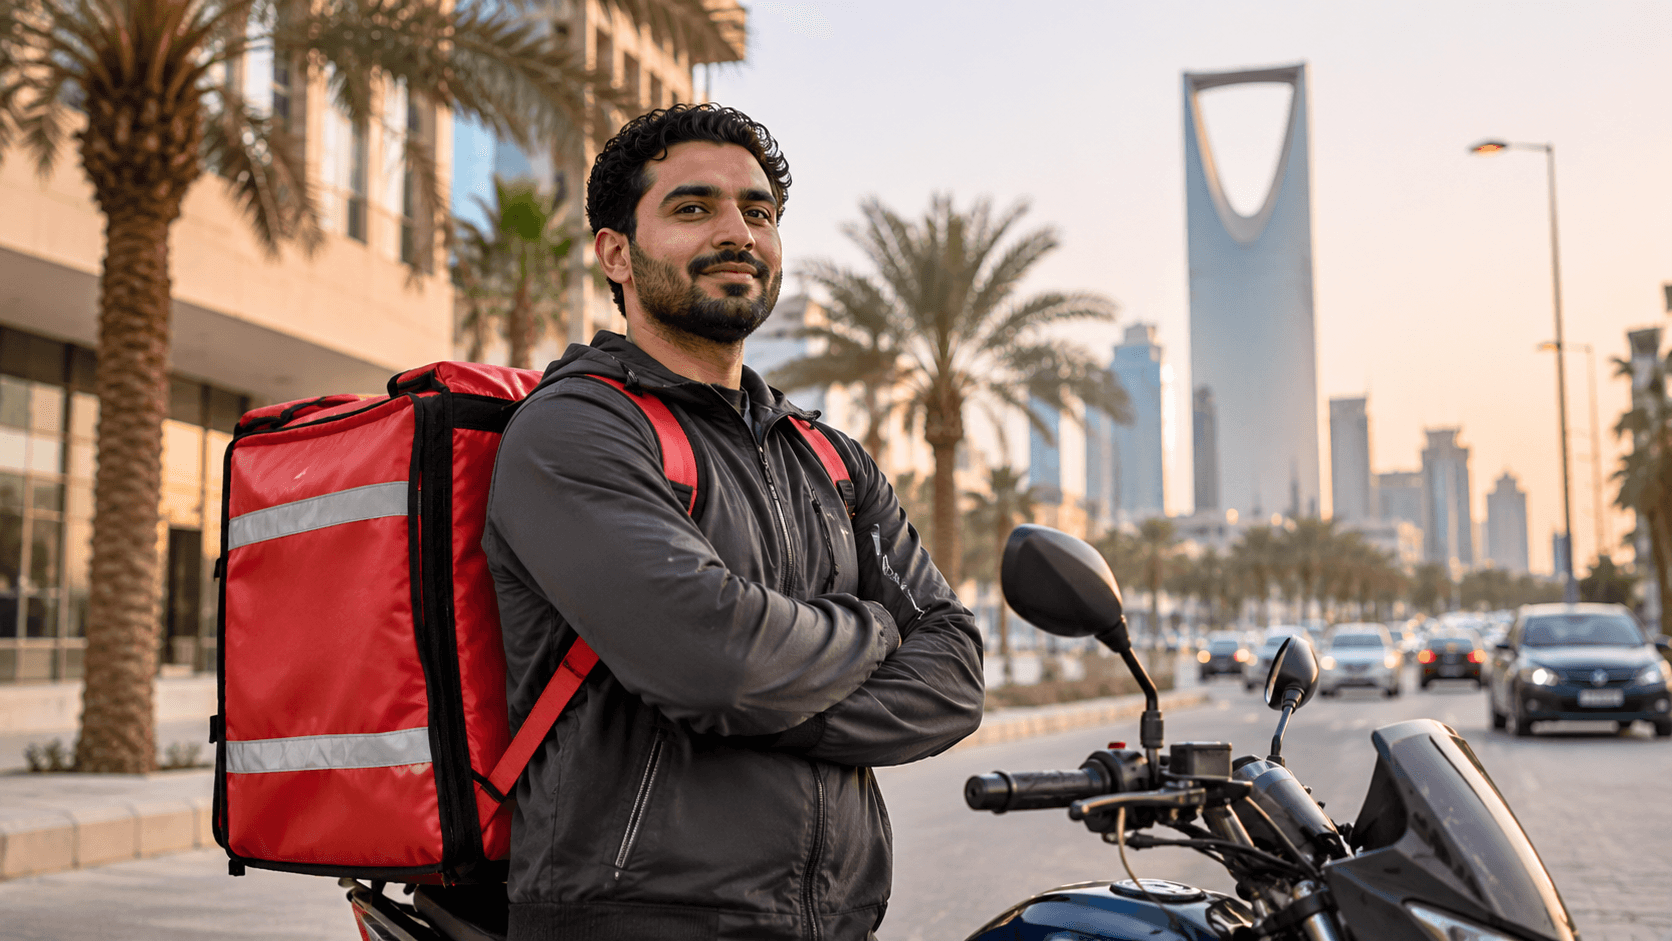
How We Crafted a Leading Saudi Food Aggregator’s Growth Strategy


Executive Summary
Saudi Arabia’s food aggregator market is set to nearly double from SAR 20 Bn to SAR 38 Bn by 2030, but the phase of hypergrowth that carried early gains is giving way to a more contested, price-sensitive stabilisation phase. A leading food delivery aggregator engaged Redseer to pinpoint exactly where its next phase of growth would come from and to understand how its customer satisfaction was tracking across segments. The engagement identified that even a conservative scenario represented an incremental SAR ~5 Bn in sales by 2030, and showed that the single most important segment for that future growth, expat users, was also where a specific and addressable set of levers could unlock it.
About the Client
The client is a leading food delivery aggregator platform in Saudi Arabia, holding a leading position in the market by value share.
The Problem Statement
The client’s overall market position had held broadly stable through the first half of 2024, but two signals sat underneath that stability: its overall customer satisfaction score had been declining, and the fastest-growing pockets of future market demand looked structurally different from where the client was currently strongest. At the same time, rising price sensitivity among consumers and aggressive new competitive moves signalled that a period of more intense, discount-led competition was approaching.
The client came to us with two linked questions: where exactly its future growth opportunity lay, and why satisfaction was softening even where its market position looked stable.
The Approach
We structured the engagement around three connected steps:
1. Opportunity and positioning sizing: quantified the client’s current and incremental market opportunity across regions and customer cohorts (locals, expats and tourists) and benchmarked its current position against where the largest pockets of future growth were expected to emerge.
2. Gap area identification: ran a structured consumer needs assessment across three dimensions, value proposition, platform experience and delivery experience, assessing the client’s performance against its closest competitor for each customer cohort (locals and expats, across the country’s major regions).
3. Recommendations and prioritisation: built a need-versus-gap framework, plotting what would most motivate switching against what most deterred it, to separate high-priority moves from lower-impact ones, and extended the same segmentation lens to marketing channel and content strategy.
The Outcomes
- The growth opportunity was large and concentrated – Around 80% of the market’s future growth was expected to come from just four customer cohorts. Our segmentation pinpointed which of these to prioritise, and in what order, to capture the largest share of that incremental demand.
- Two experience levers carried the most upside – Across nearly every customer cohort and region, two areas stood out as the highest-return improvements to the platform experience: app navigation and the loyalty programme.
- For non-users specifically, three levers mattered most – Among expat non-users, a needs-versus-gaps analysis showed that free delivery, discounts and delivery speed were simultaneously the biggest deterrents to trying the platform and the biggest potential motivators to convert, making them the clearest, highest-leverage priorities, ahead of secondary issues like loyalty programmes or rider behaviour, which were mentioned often but mattered comparatively less to actual switching decisions.
- Marketing and content strategy could be sharpened rather than broadened – Across almost every region and customer cohort, one digital channel and one content format dominated: short-form video distributed through a single platform was the consistent top performer for both awareness and content preference, suggesting the client’s marketing investment could be concentrated rather than spread evenly across channels and formats.
- The competitive environment justified urgency – Consumers were shifting towards comparing multiple platforms before ordering, and rival players were simultaneously increasing discount-led promotions, negotiating more favourable loyalty and commission terms with restaurants, and preparing to onboard a new, aggressively priced entrant. This pointed towards an intensifying, more price-competitive phase in the market, reinforcing that resolving the specific gaps was a near-term priority rather than a longer-term consideration.
Written by
KSA Food Delivery: Free Delivery Isn’t Free
Brands Beyond the Shelf: MENA Consumer Brands’ New Growth Playbook
The Online Grocery Report 2026: The Five-Way Win and What Comes Next
Unlocking the Next Wave of MENA E-commerce Growth
KSA-Hyperlocals: Moving Towards Multi-Verticality
GCC Q-commerce: Expansion & Consolidation
KSA food aggregators to deliver a million smiles

Talabat’s strategic decisions shaped by Redseer strategy consulting
36% Growth. Falling Profits. Compressed Valuations. What Changed in KSA Food Delivery in 2025?
KSA Food Delivery: What Comes Next After the Subsidy War
The Guide to Launching an Online Retail Brand in MENA
Saudi Q-com Regulations: Ending the Subsidy Era?
KSA Food Delivery: Free Delivery Isn’t Free
Brands Beyond the Shelf: MENA Consumer Brands’ New Growth Playbook
The Online Grocery Report 2026: The Five-Way Win and What Comes Next
Unlocking the Next Wave of MENA E-commerce Growth
KSA-Hyperlocals: Moving Towards Multi-Verticality
GCC Q-commerce: Expansion & Consolidation