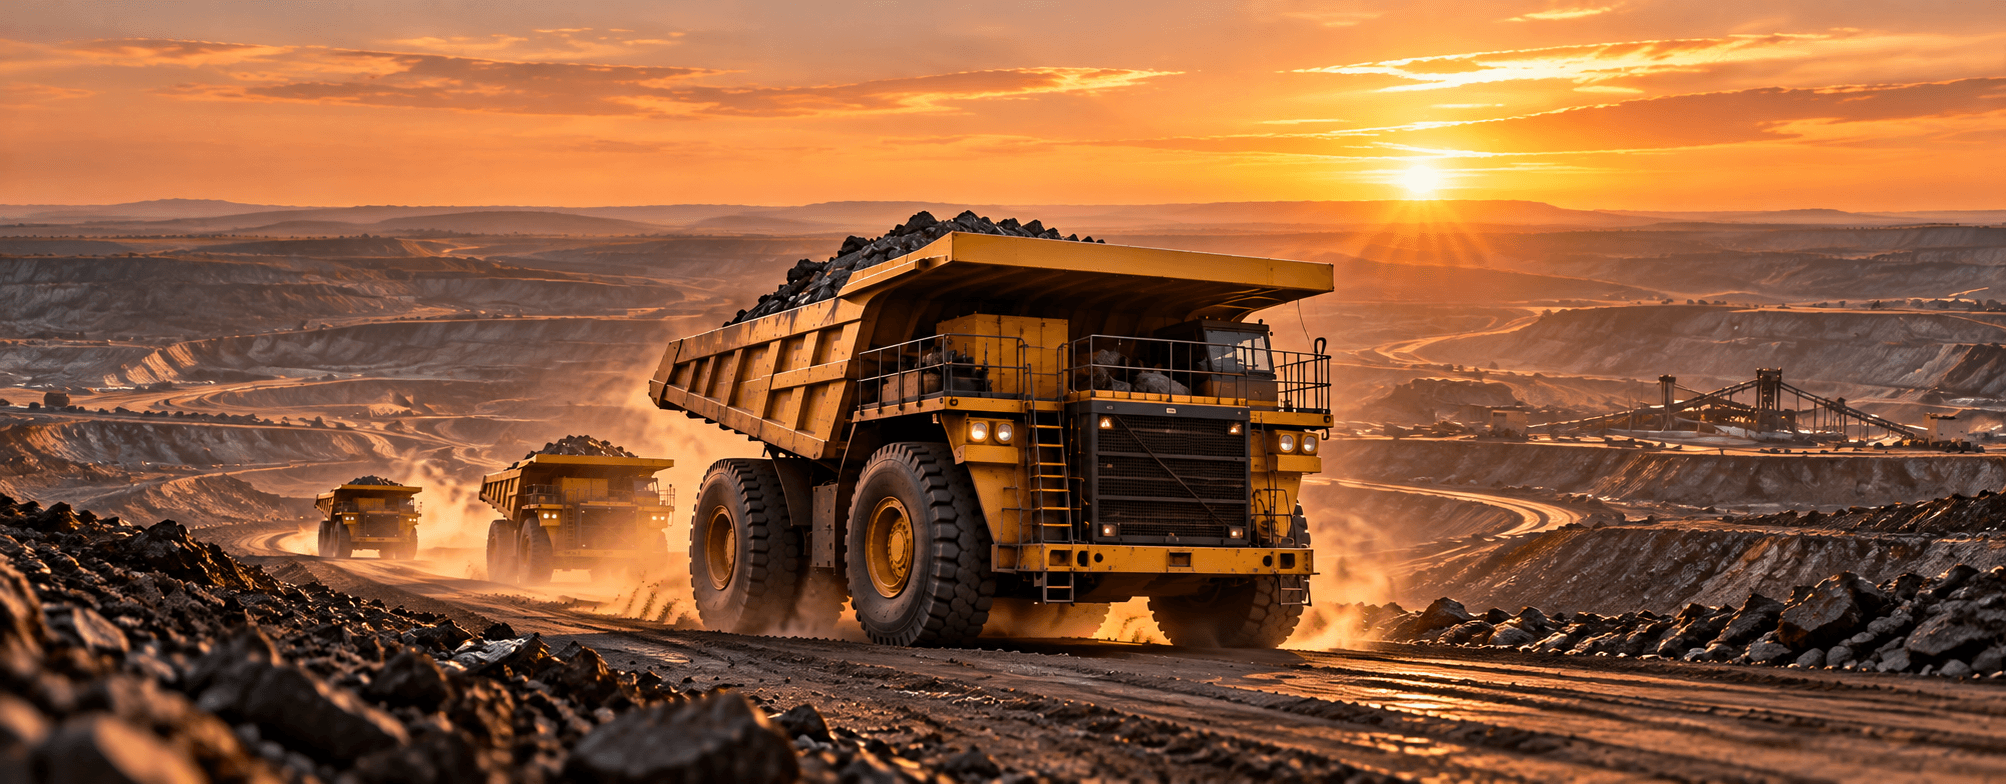
Redseer Advised a Leading Global OEM Company on its India Market Entry Strategy


Executive Summary
India’s mining equipment market is set to grow at a 12-14% CAGR over the next five years, driven by infrastructure development, new mining leases, and a shift toward higher-payload, mechanised fleets. A leading global OEM company engaged Redseer to define its India entry strategy: which segments to prioritise, how to price and finance, which customers to target, and which ownership model would best support its ambition.
The engagement produced a phased, three-stage roadmap: begin with the highest-growth mid-tonnage segment and an early electric offering, expand across the payload range once credibility is established, and build toward electric-mining-truck leadership over the long term.
About the Client
Our client is a heavy industries and mining equipment manufacturer incorporated in Singapore (with ownership and manufacturing linkages to China) evaluating entry into India’s mining truck market.
The Problem Statement
Entering a market with entrenched domestic and international competitors, tender-driven buying processes among the largest customers, and complex manufacturing and ownership trade-offs is rarely a single decision, it is a connected set of choices that need to reinforce each other. The client needed a coherent view across five linked questions: which product segments and customers to prioritize, which manufacturing model to adopt, how to price and distribute its trucks, what after-sales service model to offer, and which entry structure, and partners, would best position it for a successful, sustainable launch.
The central strategic question was: “What strategic levers must the client prioritize in its India market entry to align execution choices with its long-term ambition?”
The Approach
We structured the engagement around five connected analytical lenses:
- Market sizing and segmentation – Sized India’s mining truck market by payload capacity and by truck type, and mapped growth rates and market attractiveness for each segment.
- Competitive benchmarking: Assessed OEM market share, pricing, and product specifications across each payload segment, comparing domestic manufacturers, established international players, and recent entrants to identify where competitive intensity was low versus saturated.
- Customer segmentation analysis: Compared departmental (in-house) miners against contract miners across buying process, OEM loyalty, and openness to switching in order to identify the most viable initial customer base.
- Manufacturing and entry-model evaluation: Compared manufacturing routes and India entry structures on cost, control, speed, and long-term margin, benchmarked against how other global entrants had actually built their India presence over time.
- Regulatory and policy landscape assessment: Reviewed India’s import duty structure, foreign investment rules, emission and safety regulations, and early-stage electrification incentives to understand how each would affect the viability of different entry routes.
The Outcomes
The engagement translated into a phased strategy across every major decision area:
1. Product and customer prioritisation: We recommended entering through a high-growth, less contested payload segment with an electric variant, targeting contract miners ahead of departmental miners.
2. Manufacturing model: A phased approach, starting with imports for speed and moving towards local assembly and manufacturing as volumes grow.
3. Go-to-market and after-sales: Segment-specific pricing and a direct sales model, backed by full maintenance contracts and financing partnerships for smaller contractors.
4. Entry model: A partnership-led entry, with a path to greater ownership as the business in India matures.
Broader Takeaways
Beyond this specific engagement, several elements of the approach generalise well to other market entry strategy problems:
- Prioritize where competitive intensity is lowest, not where the market is largest. The recommended entry point was not the largest payload segment, but the one combining strong growth with comparatively low OEM saturation. For any new entrant facing an established competitive field, the fastest path to a defensible position is often through under-penetrated segments rather than head-on competition in the most contested ones.
- The easiest customer to win is not always the biggest one. Contract miners, who negotiate flexibly and switch OEMs readily, offered a faster path to initial traction than departmental miners, who are larger but locked into long, risk-averse, tender-driven relationships with incumbents. Entry sequencing that starts with structurally more accessible customers, even if individually smaller, can build credibility and reference accounts faster than chasing the largest accounts first.
- Ownership and manufacturing commitment should be phased, not fixed at entry. Rather than choosing a single permanent structure, market entry can be designed as a sequence: lower-commitment models (partnerships, joint ventures, imported products) that prioritize speed and market access early, evolving deliberately toward greater ownership, local manufacturing, and control as the business matures and margin capture becomes more important. This mirrors how several real entrants into this market built their presence over more than a decade rather than all at once.
- Manufacturing localization is fundamentally a margin decision, not only a cost or compliance one. The fastest way to enter a market is frequently also the lowest-margin way to operate long-term, while the slower, more capital-intensive routes (semi-knocked-down assembly or indigenous manufacturing) unlock meaningfully higher margins once established. Entrants need to explicitly decide how long they are willing to sacrifice margin for speed.
- Service model design can be as strategically important as product pricing. In categories where customers are making large capital equipment decisions, willingness to commit to full operational and maintenance accountability, rather than just selling the equipment, can be a meaningful differentiator and trust signal, on par with price or product specification.
Written by
Engagement Manager
The Next Battleground: Winning India’s Intracity Logistics Market Through Trust, Tech & Transparency
India’s DeepTech Renaissance: The Convergence of Defence, Robotics & Innovation Opening New Opportunities
Redseer Charted a Leading Food Delivery Platform’s Path to Leadership in Southern India
Redseer Enabled a Global Investor to Find Conviction in India’s F&O Market
How we helped a global gaming & interactive media investor read the India opportunity.
Redseer helped a leading home services platform decode the technology-led transformation of the sector
Redseer Enabled a Global Investment Firm to Assess India’s Quick Commerce Market
Redseer helped a Global Beverage Company Unlock Profitability in India’s Organised Retail
We enabled a leading e-commerce player with decision-grade intelligence on India’s online grocery market
Redseer helped a leading Indian food delivery platform identify a path to market leadership in South India
Redseer Advised a Leading Fund’s Investment in India’s Authentication, Verification & Data Privacy Market
How Redseer Helped Turtlemint Map the Case for Tech-Enabled, Assisted Insurance Distribution in India
The Next Battleground: Winning India’s Intracity Logistics Market Through Trust, Tech & Transparency
India’s DeepTech Renaissance: The Convergence of Defence, Robotics & Innovation Opening New Opportunities
Redseer Charted a Leading Food Delivery Platform’s Path to Leadership in Southern India
Redseer Enabled a Global Investor to Find Conviction in India’s F&O Market
How we helped a global gaming & interactive media investor read the India opportunity.
Redseer helped a leading home services platform decode the technology-led transformation of the sector